Buying a first home can feel like stepping into a maze of prices, competition and unfamiliar terms before you’ve even made an offer. That uncertainty is often the biggest barrier, not the finances themselves. As a first-time homebuyer, getting prequalified in California can help ease your concerns by giving you a clear, low-pressure starting point.
You don’t need to have it all figured out to start. We’re here to simplify and explain the key details so your first home feels more within reach.
What Is Mortgage Prequalification?
Prequalification is a lender’s preliminary estimate of how much you may be able to borrow, based on the financial information you provide. Knowing how to get prequalified for a mortgage doesn’t have to feel intimidating. Think of it as a no-pressure conversation, like a quick snapshot of where you stand financially before any formal paperwork begins.
As a first-time homebuyer, prequalification in California typically doesn’t require a hard credit pull and won’t commit you to any final decisions. In some cases, lenders can conduct a basic prequalification conversation in a single call or short online session. Prequalification can be a quick process. In a market where affordability is at a near-historic low for California homebuyers, it’s possibly the clearest way to find out exactly where you stand before you fall in love with a home.
What’s the Difference Between Prequalification and Preapproval?
Prequalification is relatively quick and based on the information you provide, giving you a ballpark borrowing estimate. Preapproval is a more formal process that requires verified documents and typically carries more weight with sellers. It’s worth noting that lenders don’t always use these two terms consistently. However, according to the Consumer Financial Protection Bureau (CFPB), what matters is whether your financial information was actually verified.
In a competitive market, sellers and agents often want to see at least a preapproval letter before taking an offer seriously. Prequalification is where you build that foundation.
What Do Lenders Look at During Prequalification?
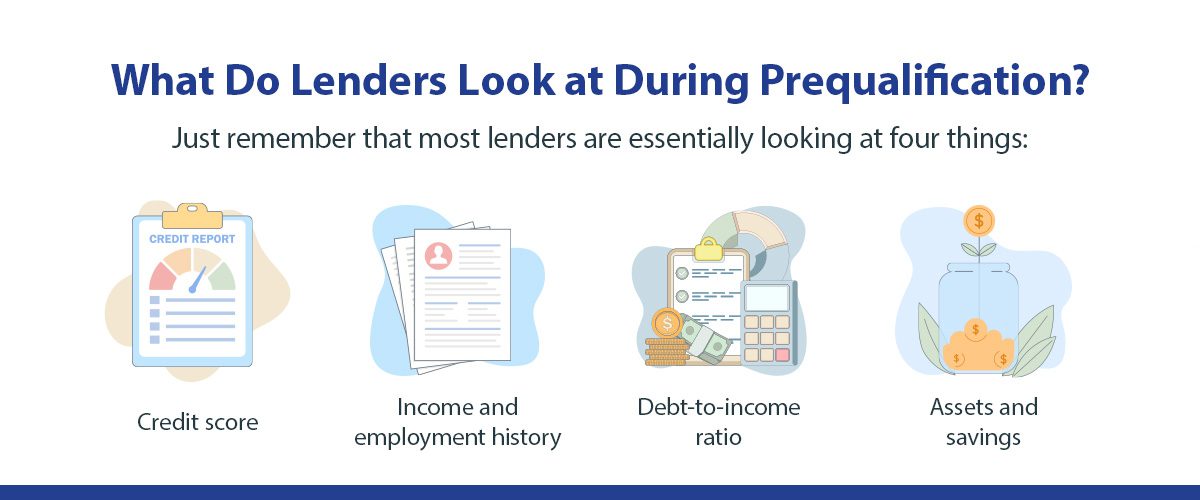
Getting a sense of what lenders review doesn’t have to feel like a mystery. Understanding first-time homebuyer requirements in California is simpler than it sounds. Just remember that most lenders are essentially looking at four things:
- Credit score: Lenders typically pull your credit scores from all three credit bureaus and use the middle score. Higher credit scores generally open more loan options and better terms. Errors on a credit report can unfairly lower a score, so checking it before starting the process is a good idea.
- Income and employment history: Lenders want to see stable income and typically look for two years of employment history. Income from employment, self-employment, and other verifiable sources may be considered, provided it’s consistent and likely to continue.
- Debt-to-income ratio: Your debt-to-income (DTI) ratio is your total monthly debt payments divided by your gross monthly income. It shows how much room remains in your budget for a mortgage payment. The lower your DTI, the more borrowing flexibility you typically have, though specific thresholds vary by loan type and lender.
- Assets and savings: Lenders want to see sufficient funds for a down payment, closing costs and reserves. With California first-time homebuyer programs, a large down payment isn’t always required.
From there, you can estimate your monthly payment using a mortgage calculator, which gives you a better idea of what to expect.
How to Get Prequalified as a First-Time Buyer in California
Getting prequalified for a mortgage as a first-time buyer may not be as complicated as you think. While the specifics will vary based on your situation, here’s what the average process looks like, from start to finish:
- Gather your basic financial information. This should include your approximate income, monthly debt payments, credit score range and any savings or down payment funds you have available.
- Contact a lender, ideally one that’s familiar with state-specific programs like CalHFA, since not all lenders are approved to offer them.
- Have a short, no obligation conversation or complete a quick online form. There shouldn’t be any formal paperwork at this stage.
- Receive your ballpark figure for how much you may be able to borrow. This should give you a clear starting point for your home search.
One thing many first-time homebuyers don’t realize is that shopping around multiple mortgage lenders within a 45-day window typically counts as a single credit inquiry. This helps to minimize any impact on your credit score.
How to Strengthen Your Prequalification Standing
Start by pulling your free credit report and reviewing it across all three credit bureaus. Look for accounts that aren’t yours, payments marked late that were made on time and duplicate debts. Errors like these can unfairly lower your score, and disputing them costs nothing.
Next, look at your credit card balances. According to the CFPB, keeping your credit utilization at no more than 30% of your total credit limit can meaningfully improve your score. If you’re carrying high balances, paying them down before you apply is one of the most impactful moves you can make.
Finally, avoid opening new credit accounts or taking on new debt in the months leading up to your application. Lenders look for consistent income over time, so a job move or pay increase could complicate verification. If a job change is unavoidable, speak to a lender first. Don’t worry about asking them common mortgage questions like this because an experienced loan team can guide you through them.
California Programs First-Time Buyers Should Know About
Several state-level programs are specifically designed to make homeownership more accessible, and knowing they exist could change what seems possible. Working with a lender who understands these programs can make all the difference in using them.
CalHFA Programs
The California Housing Finance Agency (CalHFA) is the state’s housing finance agency. It offers first-mortgage loan programs, along with down payment assistance options such as MyHome for first-time buyers. CalHFA first-time homebuyer eligibility generally requires that you haven’t owned and occupied a home in the last three years.
You’ll also need to work with a CalHFA-approved lender and complete a homebuyer education course. Minimum credit scores for CalHFA programs typically fall in the 660 to 680 range, depending on borrower income. These programs often pair with FHA or conventional financing, so it helps to understand the differences between FHA and conventional loans before choosing a path forward.
The California Dream for All Loan
The California Dream for All program takes a more targeted approach, aimed at first-generation homebuyers. To qualify, all borrowers must meet CalHFA’s first-time homebuyer requirement and at least one borrower must meet the first-generation homebuyer requirement. Generally, you can’t have owned a home in the last seven years, and your parents can’t currently own a home in the U.S.
The key benefit is down payment assistance up to 20%, capped at $150,000. It works as a shared appreciation loan, meaning that when you eventually sell the home, you repay the original assistance plus a proportionate share of the home’s appreciation.
Funding is limited, and the program typically opens in periodic windows via a randomized lottery rather than remaining open year-round. Buyers must also get preapproved through a CalHFA-approved lender before applying for a voucher. Getting prequalified and preapproved now positions you to act quickly when the next round opens.
Get Prequalified With Pacific Mortgage Group
You’ve now got a clear picture of what prequalification involves and what the state’s first-time buyer programs can offer. The next step is making it personal, and that’s where Pacific Mortgage Group comes in. With nearly two decades of experience as a California-based lender, Pacific Mortgage Group brings local market knowledge and hands-on familiarity with programs like CalHFA.
Getting started doesn’t require a stack of paperwork. It’s a short, straightforward conversation designed to give you real answers without jargon or surprises. When you’re ready, get started with Pacific Mortgage Group and take that first step. You don’t need to have everything figured out. You just need to begin! Call Pacific Mortgage Group today at 951-404-2928 to talk through your prequalification options with an experienced loan team.